Back

Buying a Home in the Fall: Why the Slower Season Can Work in Your Favor

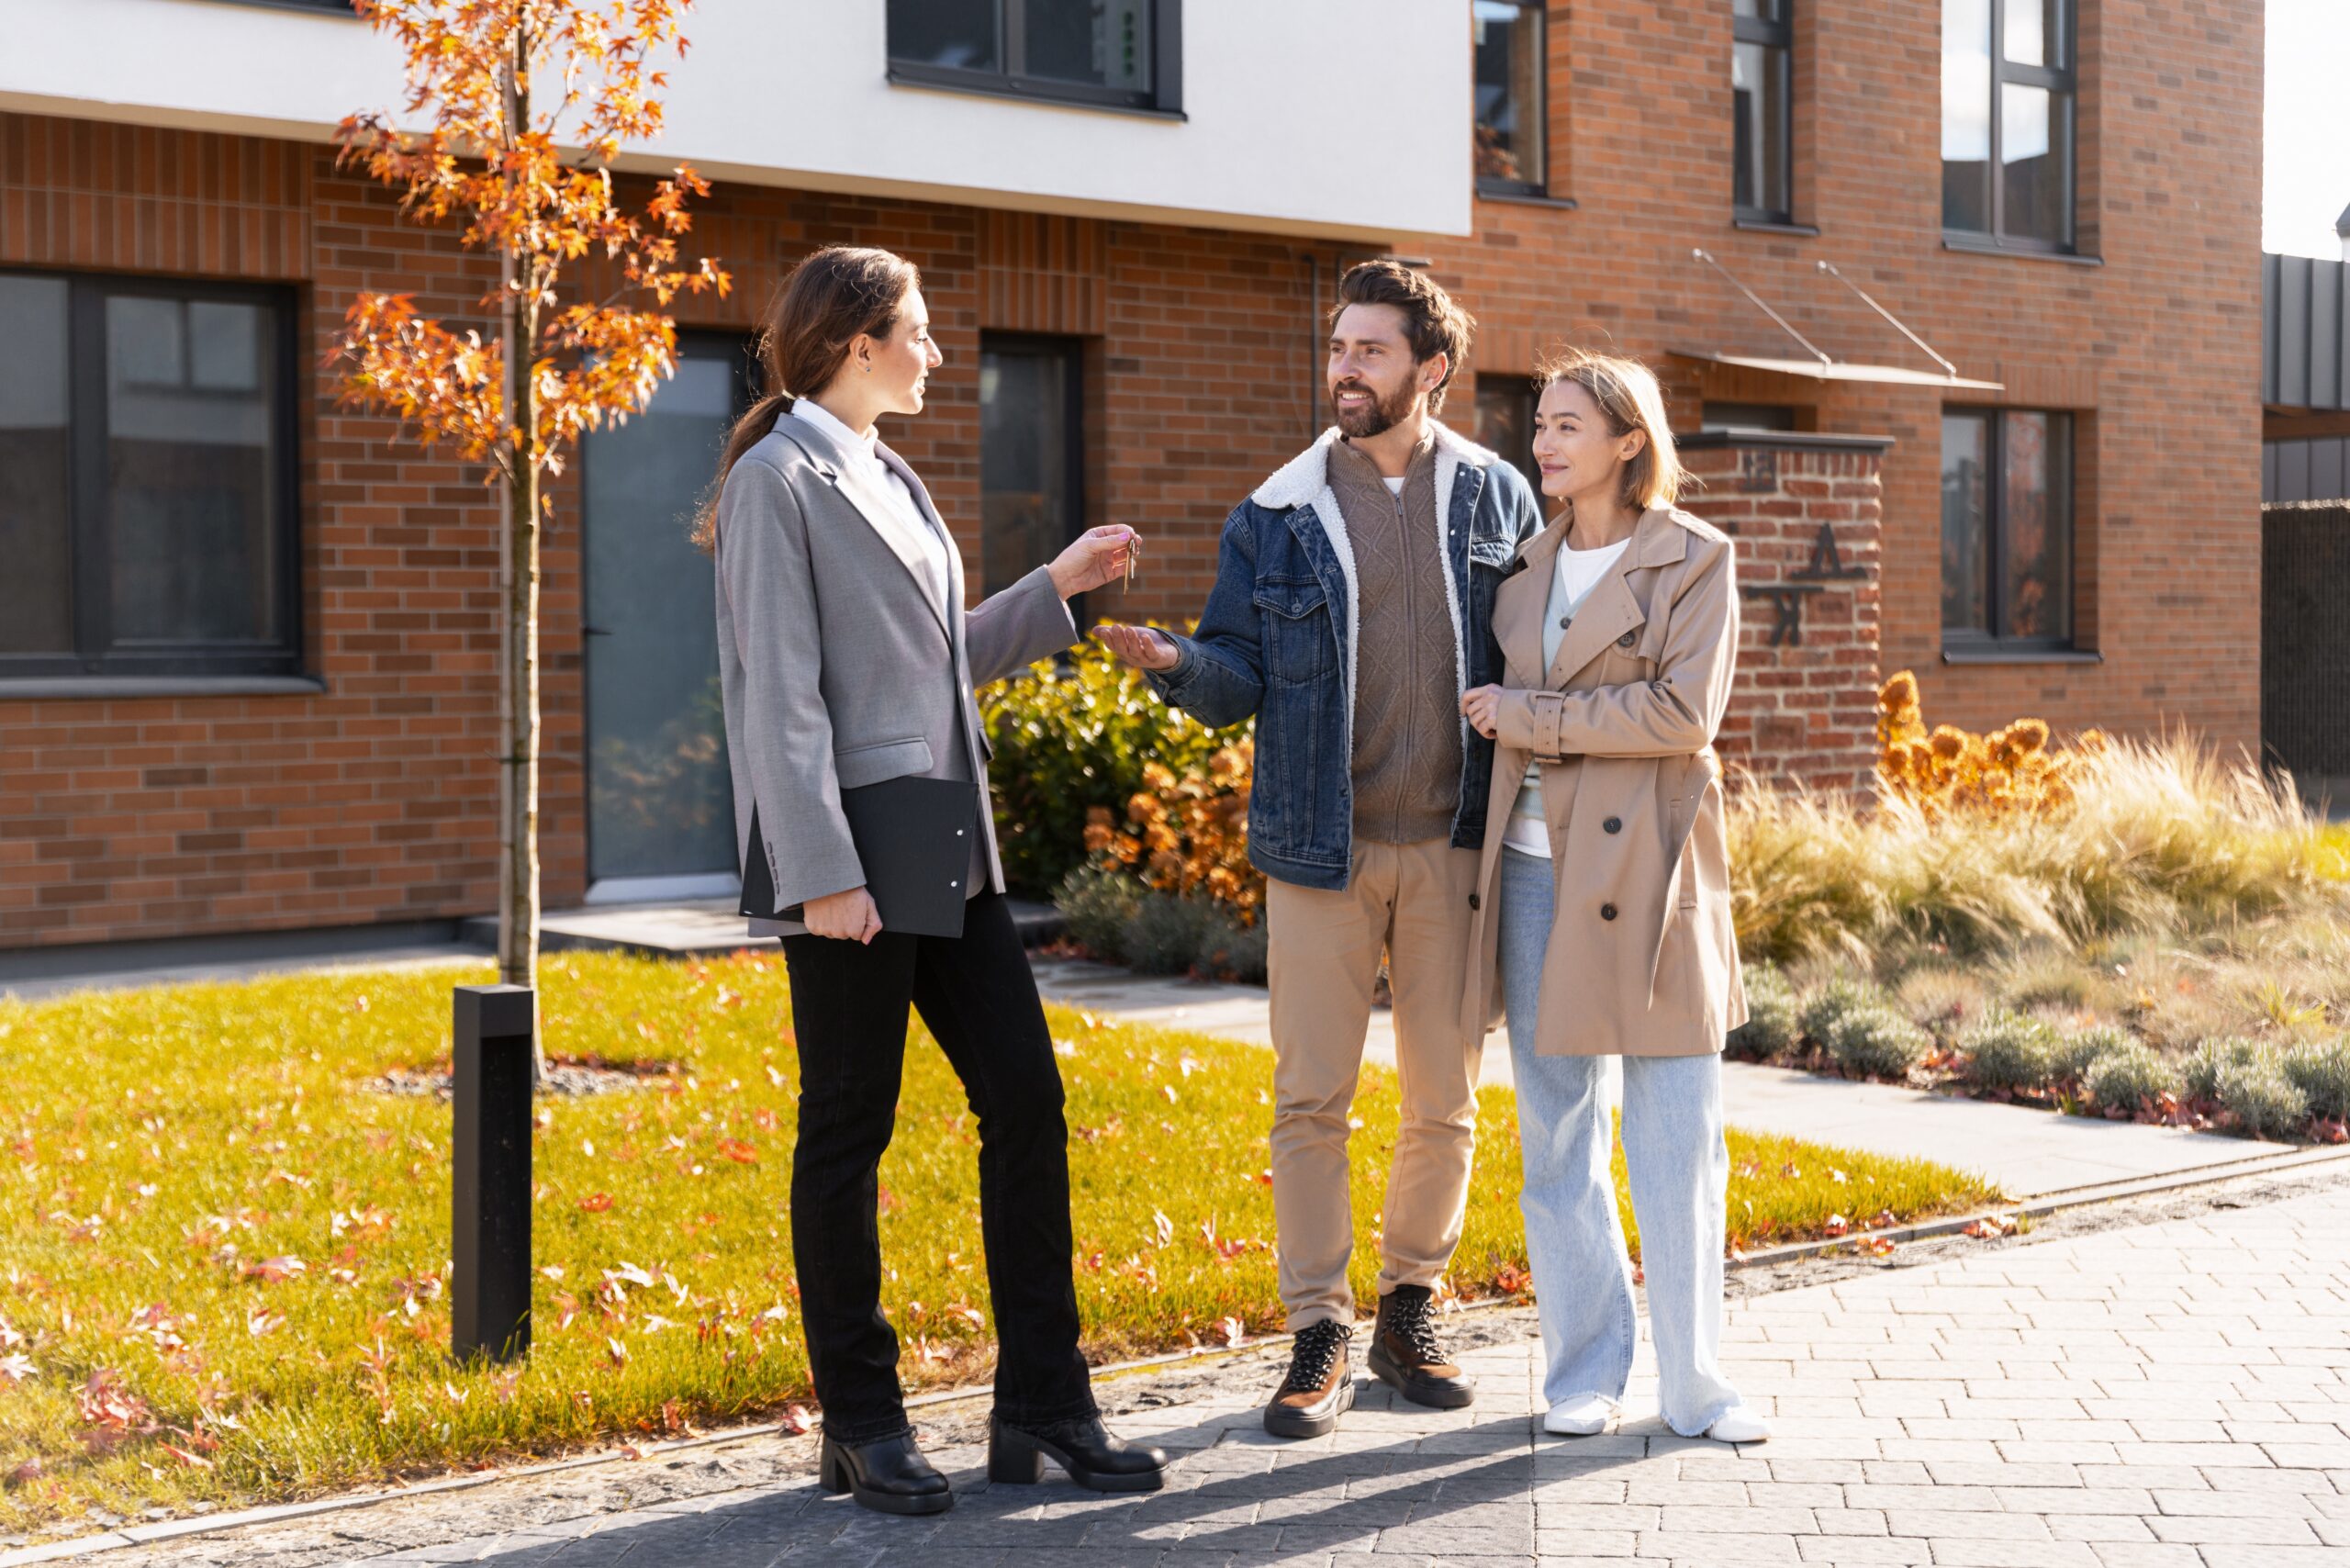
Spring gets the attention, but the fall market tends to favor buyers in ways that listing counts alone don’t show. Inventory thins out after Labor Day — and so does competition, which changes the negotiating dynamic considerably.

What shifts in the fall:

  • Fewer competing offers, as many buyers pause once the school year starts
  • Motivated sellers, particularly those whose homes sat unsold through the summer
  • Price reductions on listings that have been active for 60 days or more
  • Faster turn times, as appraisers, inspectors, and underwriters work through lighter volume

Where to be careful:

  • Thinner inventory means fewer choices, so a rigid must-have list can leave you waiting until spring
  • Daylight gets short — schedule showings and inspections while there’s still light to evaluate the roof, grading, and exterior
  • Year-end closings compress around holidays, so build buffer into your contract timeline
  • Sellers listing in the fall are often relocating on a deadline, which can cut both ways in negotiation

The fall market trades selection for leverage — fewer homes to choose from, but far less competition for the ones that are listed. Buyers who are already pre-approved and able to move quickly often secure better terms in October than the same home would have brought in May.

More articles

Get started today!

Fill out the questionnaire on this page to start a discussion about your mortgage needs today!

What are your goals?
We are committed to helping you reach them.

Where is the home located?

What type of home is it?

Where are you in the home buying process?

How do you plan to use your new home?

Have you or your spouse served in the US military?

Veterans and active US military may be eligible for a $0 down VA loan when purchasing a home.

What is your (or your spouse's) branch of military service?

Are you actively working with a real estate agent?

Is this your first time purchasing a home?

What is the approximate purchase price of the new property?

$250,000

How much do you have for a down payment?

$250,000 (25% Down)

What is your current employment status?

What is your household gross (before taxes) annual income?

What is your credit score?

Have you had a bankruptcy or foreclosure in the past 3 years?

What’s your name?

Where is the home located?

What type of home is it?

Have you or your spouse served in the US military?

Veterans and active US military may be eligible for a $0 down VA loan when purchasing a home.

What is your (or your spouse's) branch of military service?

What is the estimated value of your property?

$250,000

What is the estimated balance of your first mortgage?

$250,000

Do you have a second mortgage?

How much additional cash do you wish to borrow?

(It's OK to estimate or if no cash-out leave at $0)

$250,000

What is your current employment status?

What is your household gross (before taxes) annual income?

What is your credit score?

Have you had a bankruptcy or foreclosure in the past 3 years?

What’s your name?

NMLS ID: 1876615  MB# 1043157  Company NMLS ID:2336874


HelloLend is an Equal Housing Lender. As prohibited by federal law, we do not engage in business practices that discriminate on the basis of race, color, religion, national origin, sex, marital status, age (provided you have the capacity to enter into a binding contract), because all or part of your income may be derived from any public assistance program, or because you have, in good faith, exercised any right under the Consumer Credit Protection Act. The federal agency that administers our compliance with these federal laws is: Federal Trade Commission, Equal Credit Opportunity, Washington, DC 20580.


Consumers wishing to file a complaint against a company or a residential mortgage loan originator should complete and send a complaint form to the Texas Department of Savings and Mortgage Lending, 2601 North Lamar, Suite 201, Austin, Texas 78705. Complaint forms and instructions may be obtained from the department’s website at www.sml.texas.gov. A toll-free consumer hotline is available at 1-877-276-5550. The department maintains a recovery fund to make payments of certain actual out of pocket damages sustained by borrowers caused by acts of licensed residential mortgage loan originators. A written application for reimbursement from the recovery fund must be filed with and investigated by the department prior to the payment of a claim. For more information about the recovery fund, please consult the department’s website at www.sml.texas.gov.


The content provided within this website is presented for information purposes only. This is not a commitment to lend or extend credit. Information and/or dates are subject to change without notice. All loans are subject to credit approval. Other restrictions may apply. Mortgage loans may be arranged through third party providers.

We use cookies to enhance user experience. By accepting, you agree to our Privacy Policy.